EUDR & the Print Exemption: What’s Actually Covered - and What Isn’t
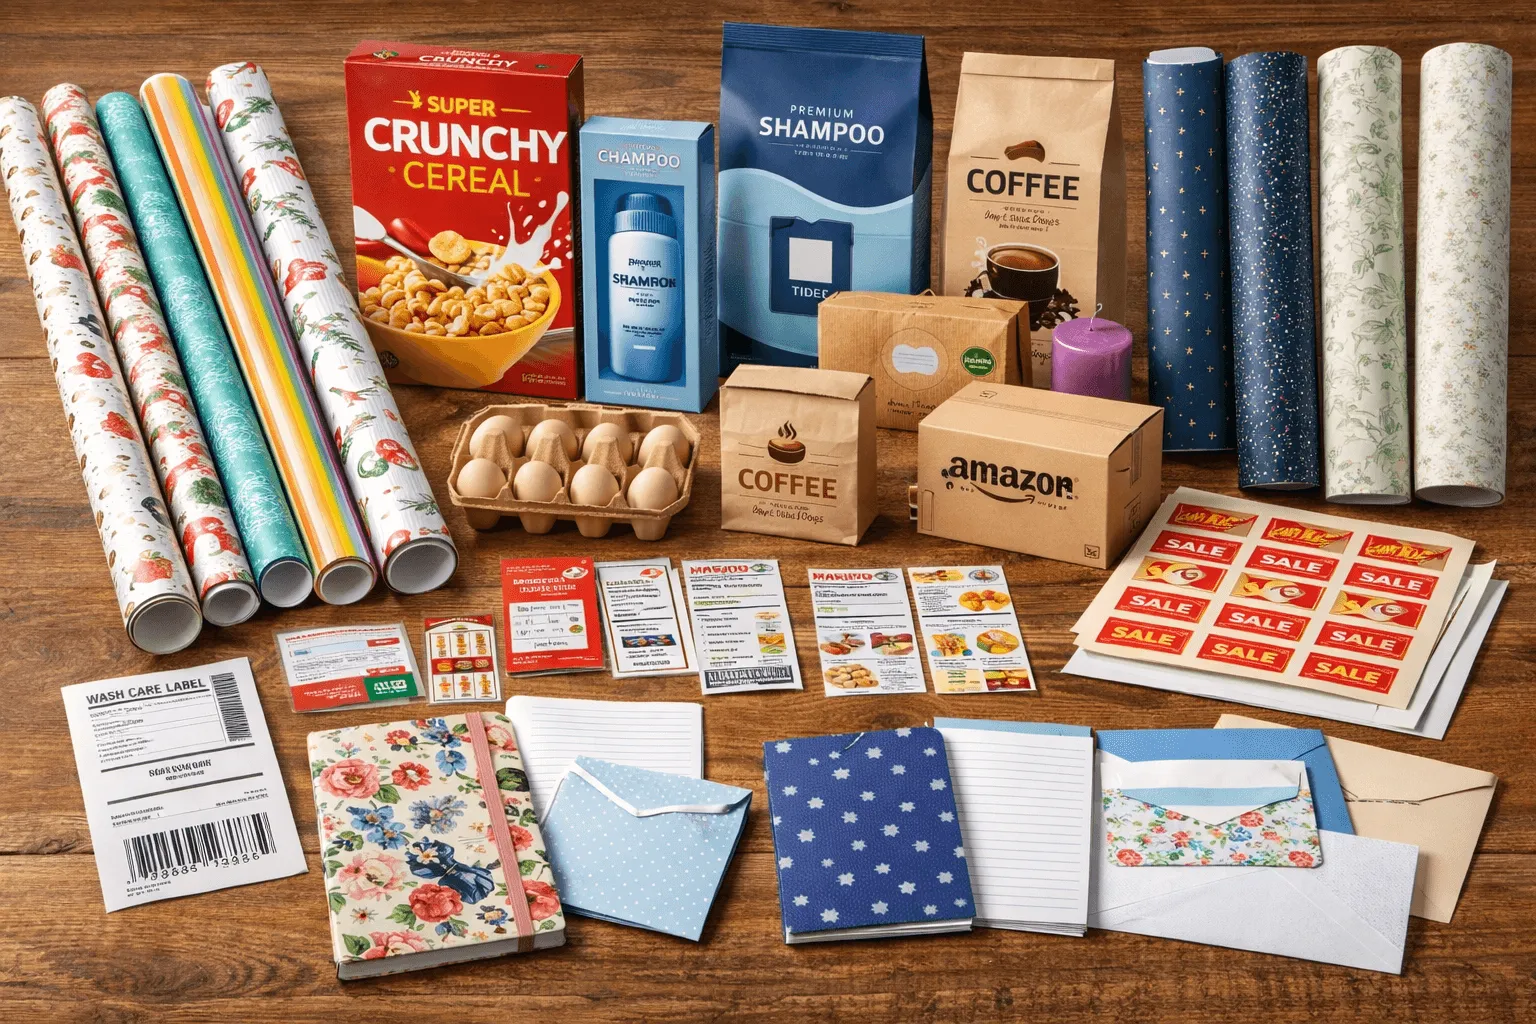
A clear breakdown of the EU’s updated “print exemption” under EUDR, explaining which printed materials are genuinely exempt under HS Code 49 and which high-volume items remain in scope under HS Code 48. Paper and Packaging Expert Trevor Willis clarifies what the 2025 changes mean for operators, downstream traders, and seasonal supply chains ahead of the 2026 enforcement deadline.
Following our recent webinar with the Department for Business and Trade, hosted by our Head of Market Development Anna Roberts, we received a wide range of questions from attendees on how the EU Deforestation Regulation (EUDR) affects UK businesses. This post is part of a series working through those questions by theme.
In this instalment, we address questions on which products and commodities fall within scope of EUDR, including specific tariff codes, packaging, gifts, and how to evidence out-of-scope components.
Watch the full webinar recording here.
Whilst the below answers specific questions, we also have an article on how to tell if your products are in scope or not here. It covers:
- Who needs to check
- How to use Annex I
- Examples in practice
- Composite products
- Common misunderstandings
- Supplier codes vs importer codes
- What to do if you are unsure
For now, here are the particular questions asked during the webinar that we hope you find useful.
Q: When talking about wood-based products, do we also need to include corrugated packaging that products are shipped in, or is it solely for the finished product?
Good news here. The Delegated Act adopted on 13 July 2026 exempts packing material, whether single-use or reusable, when it is used to support, protect or carry another product.
This means corrugated packaging used to ship products should be out of scope.
Q: What about a calendar sent from a UK company to an EU company as a gift? Is this still in scope if no charge is made?
Calendars fall under HS/CN Chapter 49 (printed products), which was removed from the scope of EUDR by the December 2025 amendment (Regulation (EU) 2025/2650). This means a calendar sent as a gift is not in scope, whether or not a charge is made.
It’s worth noting that gifting and supplying goods free of charge can still count as placing goods on the market for products that are in scope (FAQs 2.10 and 3.2), so this answer depends on the product being a Chapter 49 item.
Q: The HS code of the product we export to the EU indicates it is in scope, but we know the components of the product are outside scope. How do we evidence this to our customer and the customs authorities?
The EU buyer only needs to conduct due diligence on the in-scope components. For instance, an armchair made of wood and leather with steel components:
- Steel: not in scope, no due diligence required.
- Leather: not in scope. Cattle hides, skins and leather were removed from Annex I by the Delegated Act, so no due diligence is required.
- Wood: due diligence required.
It could be that whilst the whole product is in scope (e.g., a rubber hose), it is made of synthetic rubber, which is not in scope. Or it is packaging but made of bamboo (not in scope). It is therefore important to check the details in Annex I, paying attention to any ‘extracts of’. If the product you have in mind falls into this category, then there is a specific TARIC code (Y129) to use on customs documents.
Q: We deal with packaging that has card cores on our films and tapes. Would these be in scope and therefore need due diligence statements for the paper/card cores?
We would need to understand the HS codes the films and tapes are imported into the EU with. Even if a component of a product is in scope, if the product itself is not in scope, then there is no need to submit a DDS to TRACES or conduct due diligence. EUDR applies to the product as a whole, not specific component parts.
Q: We manufacture botanical extracts, some of which have ingredients in scope of EUDR. Are our liquid extracts in scope? Tariff codes: 3302901000, 1302197000, 2101110000.
3302901000 and 1302197000 are not in scope of EUDR.
2101110000 has been added to Annex I by the Delegated Act, which brings extracts, essences and concentrates of coffee into scope from 30 December 2027.
It sounds like you might sell HS 2101 to EU customers as a standalone extract product. In which case, from 30 December 2027, the company first placing the goods on the EU market will need to comply with EUDR in full.
It would be good to understand whether the suppliers of materials for HS 2101 are from the EU or not, as this will determine your own obligations and that of your customers. Feel free to set up a meeting with us directly and we can help to figure it out with you.
Understanding exactly which products fall in scope, and how to evidence out-of-scope components, is one of the more nuanced areas of EUDR compliance. If you’re uncertain about any of your product lines, we’d encourage you to review Annex I as amended by the Delegated Act, and to get in touch with our team if you need further guidance. The next post in this series will address questions on Due Diligence Statements and the TRACES system.
Trevor has extensive experience in the paper and packaging industry, and is passionate about fighting against counterfeiting through improved traceability and ensuring that the products EU citizens consume do not contribute to deforestation worldwide.